Connecticut’s Flood Disclosure Law: What Home Sellers Must Answer Now — and How to Still Sell
Six new questions. Every one of them is about water.
You’re getting ready to sell. Your attorney or agent slides the Residential Property Condition Report across the table, and there’s a whole section you’ve never seen before: flood risk. Is the house in a floodplain? Have you ever filed a flood claim? Did you get disaster aid? You remember the storm, the claim, the check, the summer you spent tearing out the first floor — and your stomach drops.
The Connecticut flood disclosure law that took effect July 1, 2025 changed what home sellers have to answer. If you’ve had water in the house, you’re probably wondering whether honest answers will scare off every buyer. The honest answer: some buyers will walk, and some won’t. And if the damage is still in the house, our guide to selling a water-damaged house in Shelton covers the bigger decision of whether to repair first.
This guide walks through each new question and what the $500 rule really means. It also covers an older federal rule many sellers have never heard of, and how a cash buyer like Helpful Home Buyers looks at a “yes” on the flood questions.
Get a fast, no obligation cash offer!
Fill out this form to get started on your fair all-cash offer.
Get Your Fair Cash Offer
Fill In This Form To Get Your No-Obligation All Cash Offer Started!
"*" indicates required fields
What Connecticut’s Flood Disclosure Law Changed on July 1, 2025
Connecticut has required most home sellers to fill out a Residential Property Condition Report for years, under CGS § 20-327b. In 2025, lawmakers passed Public Act 25-33, which added a “Flood Risk Awareness” section to that report, effective July 1, 2025. The report also now includes a notice about flood insurance, flood maps and flood risk.
In plain terms, the six new questions ask:
- Floodplain. Is the property in a FEMA-designated floodplain?
- Disaster aid. Have you — or, as far as you know, a prior owner — received federal or state disaster assistance for flood damage?
- Flood insurance. Is a flood insurance policy in effect on the property?
- Elevation certificate. Is a FEMA elevation certificate available?
- Claims. Have you ever filed a claim for flood damage?
- Water in the house. Has any structure on the property had water get in or been damaged because of seepage or a natural flood event?
The same law added two more changes on July 1, 2026. Insurers now have to tell homeowners and renters policyholders that their policy doesn’t cover flood, and mortgage lenders must give loan applicants a written flood notice at least 10 days before closing. Put together, Connecticut buyers now hear about flood risk from the seller, the insurer and the lender.
How to Answer the Flood Disclosure Questions Honestly
The report is based on your actual knowledge. You aren’t expected to hire an engineer to fill it out. But you are expected to tell the truth about what you know, and you can’t hide a problem just because no question used your exact words. A few places to look before you answer:
- Your flood zone. FEMA flood maps label high-risk areas with zones that start with A or V. Moderate- and lower-risk areas are B, C or X. Your insurance agent can help you read the map for your lot.
- Your insurance paperwork. Your flood policy’s declarations page shows whether coverage is in force, and your claim records show whether you ever filed for flood damage.
- Your disaster-aid records. If you took FEMA, SBA or state disaster aid for flood damage after a storm like Sandy in 2012 or the August 2024 floods, the answer is yes — and if that aid required you to carry flood insurance, the federal rule below applies to you.
- Your basement. If you know water has come in from seepage or a flood, answer yes, even if it was fixed. Be ready to explain what happened and what was repaired. Buyers will ask.
The $500 Credit — and Why Skipping the Report Doesn’t Help
Under the Connecticut statutes that govern the condition report, § 20-327c says a seller who doesn’t give the buyer the report generally has to credit the buyer $500 at closing. Some sellers see that as a cheap way out. It isn’t. Skipping the form doesn’t erase your duty not to hide a defect you know about, and hiding a known flood problem can create legal trouble that $500 never covers.
There are exemptions. Certain transfers — like court-ordered sales, some estate and fiduciary transfers, foreclosure-related transfers and gifts of the property to a spouse or close relative — don’t require the report. If you think your sale might be exempt, confirm it with your attorney before you skip anything.
CT Homeowners Love Us!
Here’s how HHB helped people move forward—quickly, quietly, and on their own terms.
Sharon Kiraly
Fairfield, CT
..he made a very fair and equitable offer to purchase my home of 30 years and was sensitive to all my cherished memories of living there, raising my family, and then parting, making it a bearable transition.
I’m very grateful to Daniel Riccio.
Louis - Macdonald
Road Trumbull, CT
The entire process ran smooth and the company was extremely accommodating to our family's needs. They were understanding and gave us the opportunity to have extra time after the sale to sort through our belongings. Whatever we no longer wanted they kindly let us keep on the property and they took care of it for us.
I would highly recommend working with them!
Karen Mavilia
Howe Ave Shelton, CT
Second time with Dan Riccio and and his all-star team -- a rental property in 2019, now my home in January 2025. Flawless synchronicity from start to finish. Downright upright ethics -- so rare today. All commitments met and expectations exceeded. 24/7 project management, impressive array of skilled contractors resolved all issues in a timely professional manner. Best of all, I simply took what I wanted and left all remaining contents.
One More Rule If You Received Federal Flood Aid
This one surprises people. It comes from a federal law, 42 U.S.C. § 5154a. If you received federal flood disaster assistance that required you to buy and keep flood insurance, you have to tell the buyer about that requirement. The notice must be in writing, in the documents that transfer the property. If you don’t, and the buyer later lets the coverage lapse, floods and receives federal disaster aid, you could be required to pay that aid back.
FEMA says the flood insurance requirement stays with the property, and in most cases an existing flood policy can transfer to the new owner with no lapse in coverage. Your closing attorney can put the right notice in your paperwork — just make sure they know about the aid.
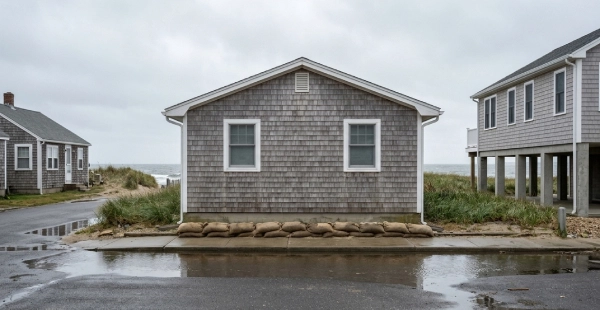
Why Flood Answers Matter More on the Milford Shoreline
If you’re selling a house in Milford near the water, check the flood map before you answer the very first question. Coastal flood maps show A zones and, right along the shore, V zones, where storm waves add to the risk. Milford’s beach neighborhoods also remember Hurricane Sandy, which led to a federal major disaster declaration covering New Haven County in 2012.
Your answers matter to buyers because of what comes next. According to FloodSmart, if a property is in a high-risk zone and the buyer has a government-backed mortgage, flood insurance is required. Under the NFIP’s Risk Rating 2.0, most premium increases on a primary home are capped at 18% a year — and a buyer will factor that bill into what they can pay. Connecticut’s official planning scenario also calls for about 20 inches of sea-level rise in Long Island Sound by 2050, so these questions aren’t going away.
How a Cash Buyer Handles a “Yes” on the Flood Questions
Here’s the part most sellers don’t expect: a “yes” doesn’t end the conversation with a cash buyer. Helpful Home Buyers reads the same condition report every buyer reads. We don’t need a lender to approve a loan, so a lender’s flood-insurance requirement or a slow appraisal doesn’t stand between you and the closing. We look at the house, the flood zone, the history and the repairs, and we put a number on it as it stands.
If the house still has damage, here’s how to sell a water-damaged home in Connecticut without repairs. If it’s in a flood zone and the damage was serious, read about how the FEMA 50% rule affects a flood-damaged house before you price any repairs. And if the water came from a pipe instead of a storm, our guide to burst-pipe water damage covers the insurance side.
Dan and Meghan, who run Helpful Home Buyers here in Connecticut, have spent more than 15 years buying houses in any condition. Honest answers on the form don’t scare them off. Hidden ones would.
Frequently Asked Questions
Navigation
→ Back to: Sell a Water-Damaged House in Shelton, CT
→ Next: Burst Pipes and Water Damage: Repair, Claim, or Sell As-Is?
→ Service area: Sell Your House in Milford, CT
Ready to Answer Every Flood Question Honestly — and Still Sell?
Fill out the condition report truthfully, then let us walk through the house once. Within 24 hours you’ll have a written, no-obligation cash offer that already accounts for the flood zone, the claims history and whatever the water left behind. Start your no-obligation cash offer — no repairs, no commissions, and a closing date you choose.